Aetherius Risk Intelligence
A deterministic, auditable downside-risk screen over SEC EDGAR filings and GDELT financial news, with a reproducible crisis backtest, an honest market-timing analysis, and a pre-registered live forward test.
The result, honestly
Replayed on 161 real archived headlines from three crises, the screen flagged every affected company before its formal failure date. But it never flagged a company before the press reported its stock already falling, and the backtest cannot say how often it raises false alarms.
So the system is fast, auditable triage of a market reaction already underway, not a predictor. The working paper (Section 4.5) shows the check and the tests that pin it.
| Event | Mechanism | Flagged before resolution | Median lead to resolution | Before market reaction |
|---|---|---|---|---|
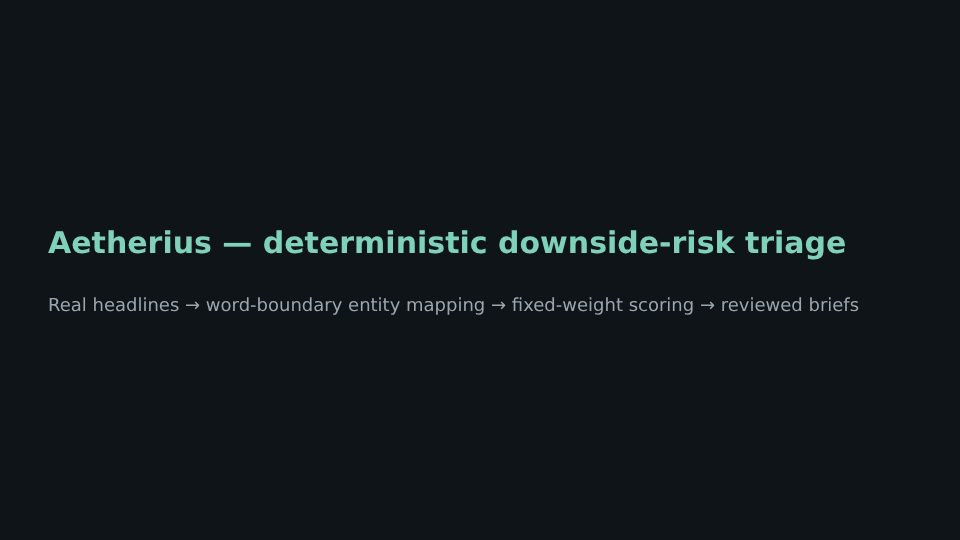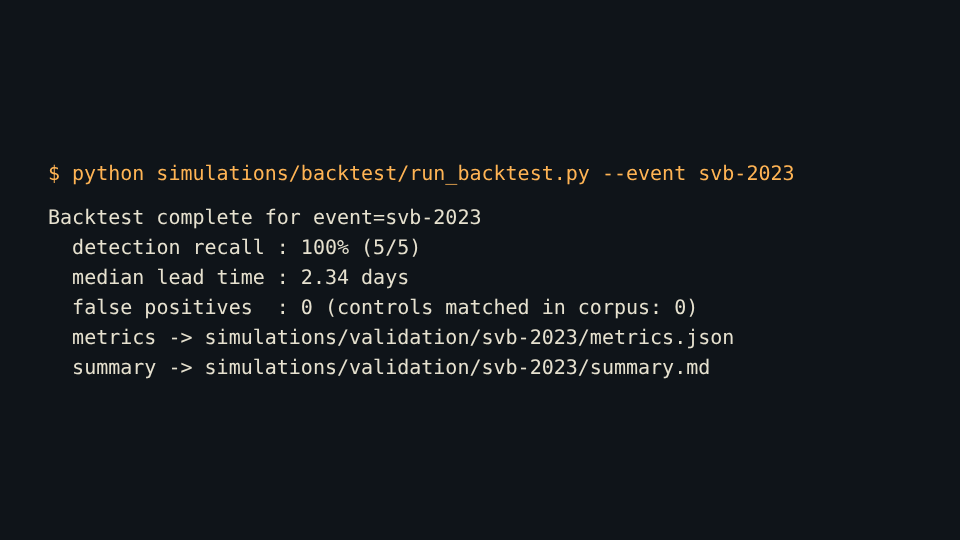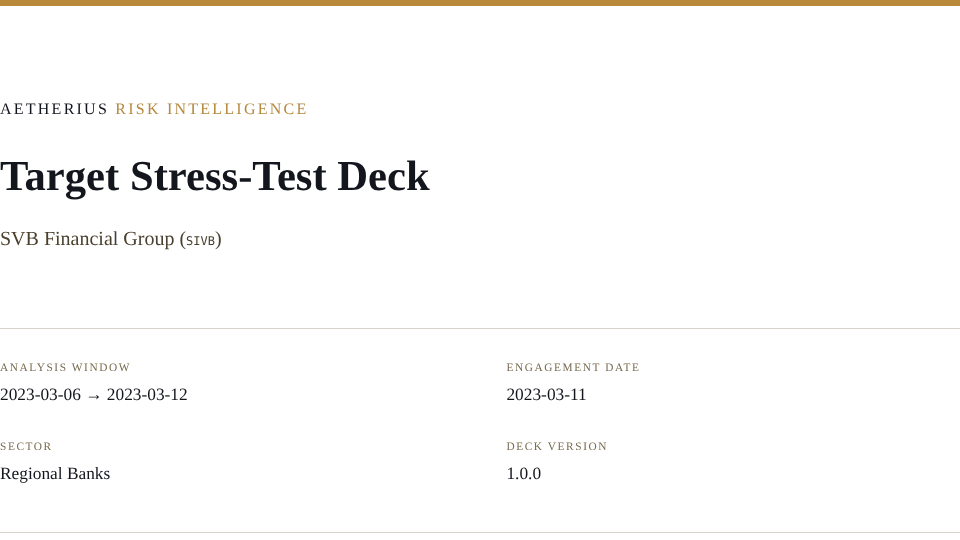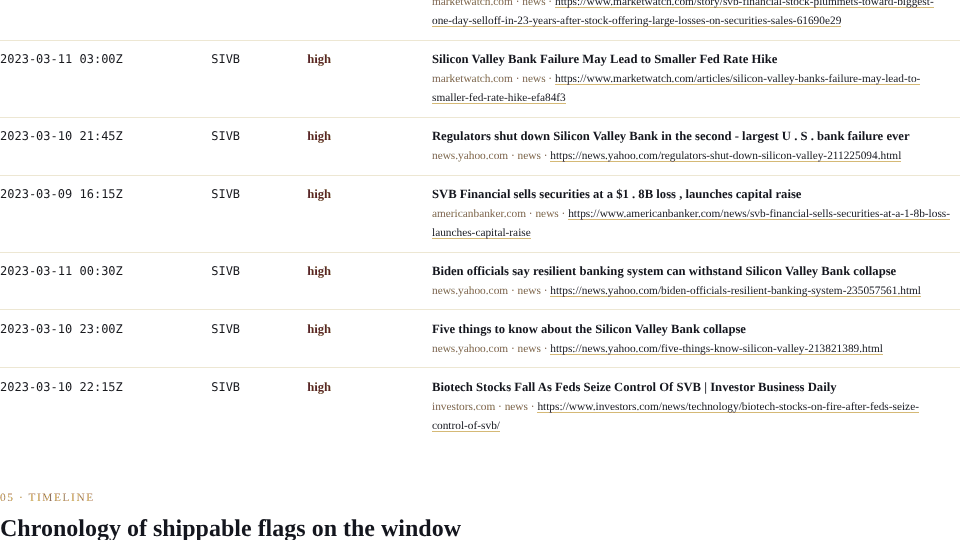
| SVB 2023 | Regional-bank contagion | 5 / 5 | 2.34 days | 0 / 5 |
| Wirecard 2020 | Accounting fraud | 1 / 1 | 6.60 days | 0 / 1 |
| FTX 2022 | Crypto counterparty contagion | 3 / 3 | 7.12 days | 0 / 3 |
How it works
Limitations
- Small sample chosen with hindsight. Three famous failures, nine names. The events and the adverse-word list were chosen knowing the outcomes.
- False alarms untested. Each event has a control company, but none appears in its headlines, so "no control was flagged" proves nothing. The live forward test measures this.
- Known false positives. Tickers that are English words match ordinary text ("coin prices fall" matches Coinbase), and adverse terms match inside longer words.
- Filings add provenance, not signal. SEC filings are scored on form type and date, not their text.
The live forward test
On 2026-10-16, before collecting any data, I committed a fixed list of 20 large US companies. Every day a GitHub Action scores live news and filings with the frozen model and commits the results. Because the record is append-only and timestamped by git, it can't be quietly edited afterwards. It will show how often the screen raises false alarms when nothing is happening, which the backtest cannot.
Run it yourself
git clone https://github.com/zariffromlatif/Aetherius-Risk-Intelligence.git
cd Aetherius-Risk-Intelligence
pip install -r requirements.txt
pytest aetherius/tests -q
python simulations/backtest/run_backtest.py --event svb-2023
About
Built by Zarif Latif as a study in building auditable data systems and evaluating them honestly. Python, FastAPI, PostgreSQL, Celery and GitHub Actions. Feedback, especially critical feedback, is welcome: zarif.latif.biz@gmail.com.